RP Select Opportunities
| 1 MON | 3 MON | 6 MON | YTD | 1 YR | 3 YR | 5 YR | 10 YR | Since Inception | |
|---|---|---|---|---|---|---|---|---|---|
| RP Select Opportunities Strategy | -3.86% | -4.09% | -1.19% | 3.12% | -2.38% | 5.52% | 5.17% | 7.28% | 7.25% |
Source: RPIA. Data as of 9/30/2026. SOF = RP Select Opportunities. SI = 04/2014. RP Select Opportunities strategy performance presented above is a hypothetical illustration based on the weighted average composite return of a separately managed account utilizing a similar strategy from inception in April 2014 to May 2014, then linked to the returns of RP Select Opportunities Cayman Fund Ltd. – Class C Lead.
SOF returned -4.09% during the quarter as both investment-grade and high yield credit spread continued to widened modestly.
Fixed income markets came under pressure during the third quarter, with the sell-off accelerating in September as resilient US growth, persistent inflation concerns, and higher oil prices pushed government yields higher. US yields moved higher across the curve, with the front end leading as markets repriced the path of monetary policy, before longer maturities came under pressure from higher term premiums, fiscal concerns, and heavy supply. Canada and Europe also weakened, although the drivers were somewhat different: Canada faced a more restrictive policy backdrop despite weaker growth, while European rates were increasingly influenced by energy-related inflation concerns. Against this backdrop, SOF’s relatively low rate duration helped mitigate the impact of the broader rates sell-off.
Credit was the more important driver of performance. High yield spreads were relatively resilient through much of the quarter, supported by strong demand and healthy corporate fundamentals, before widening sharply in September as higher rates, heavy issuance, and growing concerns around highly levered issuers pressured the market. Performance was highly dispersed across the portfolio, with Financials being the strongest sector contributor, while communications, industrials and real estate were the main detractors. Among the largest individual detractors were Avianca, CPI Property Group, CoreWeave, and MPT, reflecting a combination of sector-specific weakness, higher financing costs, and technical pressure. AI-related credit was particularly challenged as the scale of required capital spending drove substantial new issuance and increased scrutiny of leverage and returns. That being said, a few high yield issuers such as Burford still generated strong returns, which highlighted the benefit of security selection in a market where dispersion increased materially.
The portfolio’s diversified hedging overlay remained an important part of the strategy during the quarter. Credit hedges and single-name shorts helped cushion losses from the broader widening in high yield spreads and preserved capacity to add risk as valuations became more attractive. The portfolio also continued to participate selectively in new issues, where elevated supply and new-issue concessions provided opportunities to establish positions at attractive spreads. Sopaipilla is one example of a successful new issuance trade during the quarter. The A-rated data center debt is backed by a BlackRock-led joint venture, with Meta as the tenant. We participated in the new issuance at an attractive spread and fully monetized the position following substantial spread compression.
| Top Contributors to Credit Return (Sector) |
|---|
| Financials |
| Consumer Staples |
| Materials |
Source: RPIA. Data as of 9/30/2026.
| Top Contributors to Credit Return (Issuer) |
|---|
| Burford Capital Global Finance LLC |
| Western Alliance Bank |
| Sopaipilla Investor Inc. |
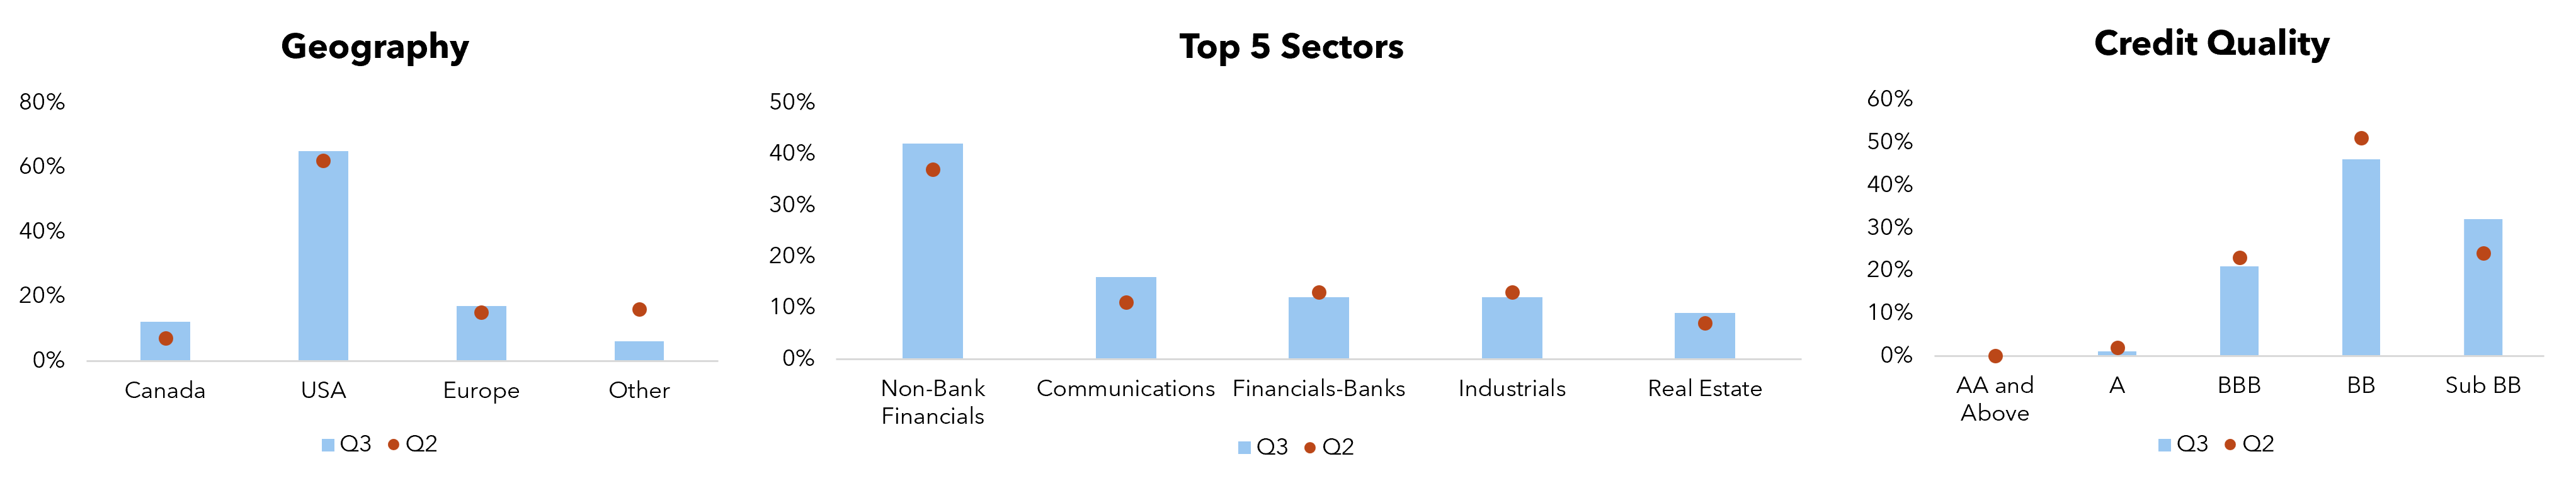
The portfolio remained active throughout the quarter, using periods of spread strength to monetize gains and periods of weakness to add selectively to high-conviction opportunities. Credit duration was reduced to ~2.3 years and net credit leverage to ~1.1x, while the portfolio remained deliberately concentrated in BB and B-rated credit and maintained essentially no exposure to the most speculative part of the high yield market. The portfolio also continued to rotate within financials, increasing exposure to specialty finance and BDCs while reducing selected bank and insurance positions. In AI and data-centre credit, the approach has been similarly selective, favouring issuers and structures with stronger protections and nearer-term catalysts rather than broad exposure to the theme.
Rates positioning was actively managed alongside the credit book. The portfolio remained constructive on shorter and intermediate US rates, where higher yields and increasingly restrictive policy pricing provided attractive carry and potential for capital appreciation, while duration was reduced as the September sell-off became more persistent. Canadian and European exposure was managed more tactically as relative value shifted. This active management allowed the portfolio to maintain meaningful rate exposure where the opportunity remained compelling without taking broad directional risk.
At quarter-end, SOF remained positioned toward higher-quality high yield, with a continued bias toward BB and B-rated issuers and limited exposure to the most vulnerable lower-quality credits. Overall credit exposure remained measured, supported by an active hedging overlay and a willingness to rotate risk rather than simply maintain static exposure. The portfolio remains focused on combining attractive carry (~10% as of Q3) with idiosyncratic opportunities and downside protection, while retaining the flexibility to add credit as market dislocations create more compelling entry points.
| Q3 2026 | Q2 2026 | |
|---|---|---|
| Effective Duration (Years) | 1.8 | 4.5 |
| Credit Duration (Years) | 3.5 | 2.8 |
| Net Credit Leverage | 1.5x | 1.2x |
| % Rated Investment Grade | 21% | 25% |
| Diversified Hedging Overlay (% of NAV) | -36% | -46% |
Source: RPIA. Data as of 9/30/2026.
Source: RPIA. Data as of 9/30/2026.
RP Debt Opportunities
| 1 MON | 3 MON | 6 MON | YTD | 1 YR | 3 YR | 5 YR | 10 YR | Since Inception | |
|---|---|---|---|---|---|---|---|---|---|
| RP Debt Opportunities | -2.02% | -2.38% | -0.48% | -1.57% | -1.50% | 4.89% | 4.23% | 4.80% | 7.17% |
Source: RPIA. Data as of 9/30/2026. DOF = RP Debt Opportunities. SI = 10/2009. Strategy performance represents the historical composite Class S returns of RP Debt Opportunities Fund LP from October 2009 to March 2011 and RP Debt Opportunities Fund Trust from April 2011 onwards.
DOF returned -2.38% during the quarter. Credit spread movements contributed to most of the mark-to-market drawdown.
Fixed income markets came under pressure during the third quarter, with the sell-off accelerating in September as resilient US growth, persistent inflation concerns and higher oil prices drove expectations for tighter monetary policy. US yields rose across the curve, led initially by the front end as markets repriced the Fed path, before pressure broadened to longer maturities amid fiscal and supply concerns. In Canada, weaker underlying growth created greater divergence from the US policy outlook, while European rates also moved higher as energy prices added to inflation concerns.
Both rates and credit detracted during the quarter. Investment-grade credit was relatively resilient through July and August despite rising yields, before spreads widened more meaningfully in September as rate volatility and heavy issuance weighed on the market. Credit losses were concentrated in communications and technology. Paramount Skydance was a notable detractor as its proposed acquisition of Warner Bros. Discovery raised more concerns around leverage, financing needs and execution, although our underlying view on the combined company's deleveraging potential remains intact. AI-related credit also weakened as substantial financing requirements drove heavy supply and increased scrutiny around the pace and returns of AI capital spending. Rather than exiting the theme, we have continued to differentiate across issuers and structures, rotating toward areas where we see stronger downside protection.
The portfolio’s diversified hedging overlay was a net detractor during the quarter, but provided meaningful downside protection as credit spreads widened more broadly toward quarter-end. The Strategy also remained active in a heavy new-issue market, where elevated supply created attractive concessions and opportunities to replace existing holdings with better-priced securities. Sopaipilla is one example of a successful new issuance trade during the quarter. The A-rated data center debt is backed by a BlackRock-led joint venture, with Meta as the tenant. We participated in the new issuance at an attractive spread and fully monetized the position following substantial spread compression.
| Top Contributors to Credit Return (Sector) |
|---|
| Health Care |
| Utilities |
| Consumer Staples |
Source: RPIA. Data as of 9/30/2026.
| Top Contributors to Credit Return (Issuer) |
|---|
| Sopaipilla Investor LLC |
| Heimstaden Bostad AB |
| Coty Inc. |
Rates positioning was actively adjusted as yields moved higher. We remained constructive on duration but reduced exposure as the sell-off accelerated, before selectively adding back at more attractive levels. In the US, the portfolio continued to favour the 2–5 year part of the curve, where higher yields and increasingly restrictive policy pricing offered attractive risk/reward. Canadian duration was reduced as the Bank of Canada became more hawkish, while positioning in Europe remained more tactical given greater sensitivity to energy prices and inflation. Overall duration ended the quarter lower as we moderated risk in response to the persistence of the rates sell-off.
Credit exposure was also actively reduced and rebuilt through the quarter rather than maintained at a constant level. We added risk during periods of weakness and monetized positions as spreads recovered, while increasingly favouring higher-quality credit. Within AI, exposure was rotated away from more supply-sensitive long-dated corporate bonds toward shorter maturities and structures with stronger collateral or contractual protections. We also increased exposure selectively in areas such as infrastructure and higher-quality financials as wider spreads created better entry points.
At quarter-end, the portfolio remains positioned up in quality, with lower credit exposure and duration than earlier in the quarter while retaining attractive carry. We continue to see opportunities in both rates and individual credits, but remain cautious given tight index-level spreads, elevated rate volatility and geopolitical uncertainty. The portfolio also continues to carry a sizeable and diversified hedging overlay, providing downside protection while preserving the flexibility to add risk as more attractive opportunities emerge.
| Q3 2026 | Q2 2026 | |
|---|---|---|
| Effective Duration (Years) | 2.3 | 2.4 |
| Credit Duration (Years) | 4.1 | 5.3 |
| Net Credit Leverage | 1.5x | 1.4x |
| % Rated Investment Grade | 91% | 95% |
Source: RPIA. Data as of 9/30/2026.
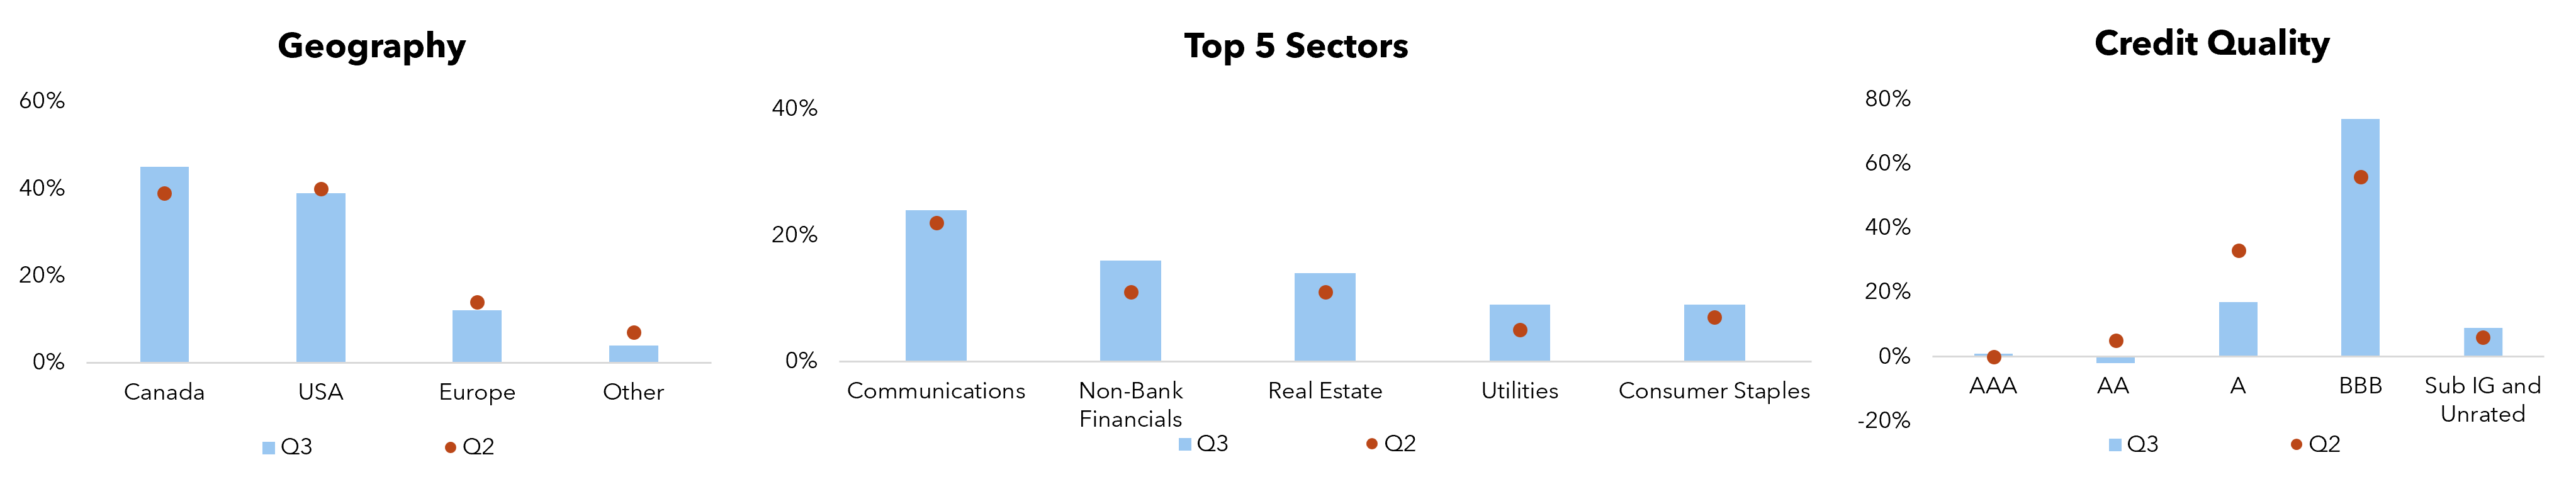
Source: RPIA. Data as of 9/30/2026.
RP Fixed Income Plus
| 1 Mo | 3 Mo | YTD | 1 Yr | 3 Yr | 5 Yr | 10 Yr | Since Inception | |
|---|---|---|---|---|---|---|---|---|
| RP Fixed Income Plus | -0.90% | -1.16% | 0.08% | 0.59% | 5.07% | 3.44% | 2.98% | 4.15% |
| FTSE Canada Universe Short Term Bond Index | -0.68% | -0.91% | 0.52% | 0.85% | 4.74% | 2.05% | 1.96% | 2.26% |
| Added Value | -0.22% | -0.25% | -0.44% | -0.26% | -0.33% | +1.39% | +1.02% | +1.89% |
Source: RPIA. FTSE Russell. Data as of 9/30/2026 and
annualized for periods greater than one year
. SI = 07/2010. RP Fixed Income Plus strategy performance presented above represents a weighted-average composite return of separately managed accounts utilizing a similar strategy from inception in July 2010 to April 2013 and linked to the returns of the RP Fixed Income Plus Fund, Series A thereafter.
FIP returned -1.16% during the quarter, underperforming the FTSE Canada Universe Short-Term Bond Index (the “Index”).
Fixed income markets came under pressure during the third quarter, with the sell-off accelerating in September as resilient economic data, persistent inflation concerns, and higher energy prices drove expectations for tighter monetary policy. The move was most pronounced at the front end of the yield curve, where markets priced a more aggressive path for both the Fed and Bank of Canada, while longer-term yields also moved higher amid persistent fiscal and supply concerns. Against this backdrop, FIP was negatively affected by rising government bond yields. Credit was considerably more resilient, as strong demand for attractive all-in yields helped limit broader spread widening.
Credit performance was mixed beneath the surface. Communications, utilities, and consumer staples were the strongest contributors, supported by select positions including Alphabet and Rogers Communications. Financials were the primary detractor, as higher rates and renewed concerns around select insurance and financial issuers weighed on spreads. More broadly, investment-grade credit remained relatively resilient despite the sharp move in rates and heavy issuance during the quarter, reflecting healthy corporate fundamentals and continued demand from yield-focused investors.
| Top Contributors to Credit Return (Sector) |
|---|
| Communications |
| Utilities |
| Consumer Staples |
Source: RPIA. Data as of 9/30/2026.
| Top Contributors to Credit Return (Issuer) |
|---|
| Alphabet Inc. |
| Rogers Communications Inc. |
| Ford Credit Canada Co. |
The Strategy remained focused on high-quality, short-duration credit while becoming more selective as the quarter progressed. Credit duration declined modestly to 2.4 years, while overall duration increased to 3.0 years as higher government yields created more attractive opportunities to add rate exposure. Within credit, exposure was reduced in financials and communications and increased across utilities and select high-quality corporate issuers, while overall investment-grade exposure remained at 100%. At quarter-end, the portfolio remained positioned to benefit from attractive carry while retaining flexibility to rotate across issuers and sectors as higher rates and greater market dispersion create more compelling entry points.
| Q3 2026 | Q2 2026 | |
|---|---|---|
| Yield to Maturity (CAD Hedged) | 4.2% | 3.5% |
| Effective Duration (Years) | 3.0 | 2.8 |
| Credit Duration (Years) | 2.4 | 2.5 |
| Average Term (Years) | 3.3 | 3.0 |
| % Rated Investment Grade | 100% | 100% |
Source: RPIA. Data as of 9/30/2026.
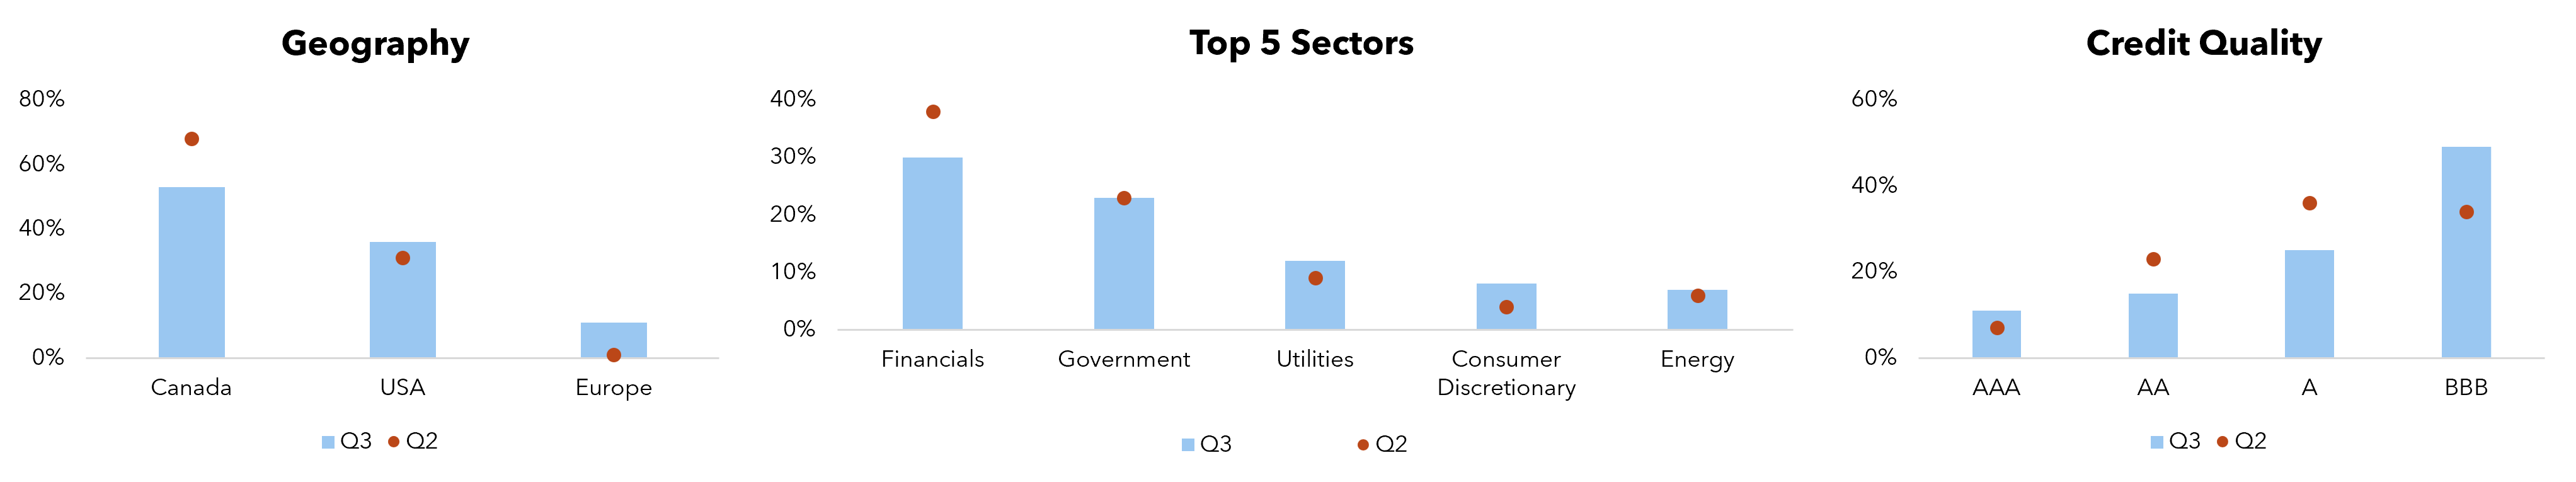
Source: RPIA. Data as of 9/30/2026.
RP Yield Advantage Fund
| 1 MON | 3 MON | 6 MON | YTD | 1 YR | 3 YR | 5 YR | Since Inception | |
|---|---|---|---|---|---|---|---|---|
| RP Yield Advantage | -0.46% | -0.48% | 0.52% | 0.28% | 0.98% | 4.53% | N/A | 4.42% |
Source: RPIA. Data as of 9/30/2026 and annualized for periods greater than one year. SI = 08/2023.
YAF returned -0.48% during the quarter, in line with the FTSE Canada Universe Short-Term Bond Index (the “Index”).
Fixed income markets came under pressure during the third quarter, with the sell-off accelerating in September as resilient economic data, persistent inflation concerns, and higher energy prices drove expectations for tighter monetary policy. The move was most pronounced at the front end of the yield curve, where markets priced a more aggressive path for both the Fed and Bank of Canada. YAF’s short-duration profile helped limit the impact of rising rates, while credit was modestly flat over the quarter as strong demand for high-quality, short-dated bonds helped contain the impact of wider spreads.
Credit performance was mixed beneath the surface. Consumer discretionary, health care and real estate were the strongest contributors, led by positions including Toyota Motor Credit, CVS Health and Athene. Financials and utilities also contributed positively, while communications was the main detractor, driven primarily by weakness in Comcast and Verizon. More broadly, higher-quality short-duration credit remained relatively resilient despite the sharp repricing in government yields, supported by healthy corporate fundamentals and continued investor demand for attractive all-in yields.
| Top Contributors to Credit Return (Sector) |
|---|
| Consumer Discretionary |
| Health Care |
| Real Estate |
Source: RPIA. Data as of 9/30/2026.
| Top Contributors to Credit Return (Issuer) |
|---|
| CVS Health Corp. |
| Toyota Motor Credit Corp. |
| Athene Global Funding |
The Strategy maintained its high-quality, short-duration profile throughout the quarter, with average maturity remaining below two years and the portfolio continuing to be entirely investment grade. Capital was selectively rotated toward discounted bonds across financials and consumer discretionary issuers, alongside additions in health care and industrials. The portfolio remains focused on identifying discounted short-dated securities offering attractive all-in yields, and maintains an average portfolio price of $93.5, well below par. This allows a greater portion of the expected return to be generated through capital appreciation as the bonds approach maturity, supporting a more tax-efficient return profile.
| Q3 2026 | Q2 2026 | |
|---|---|---|
| Yield (CAD Hedged) | 3.7% | 3.0% |
| Effective Duration (Years) | 1.9 | 1.8 |
| Credit Duration (Years) | 1.9 | 1.8 |
| Average Term (Years) | 2.0 | 1.8 |
| % Rated Investment Grade | 100% | 100% |
Source: RPIA. Data as of 9/30/2026.
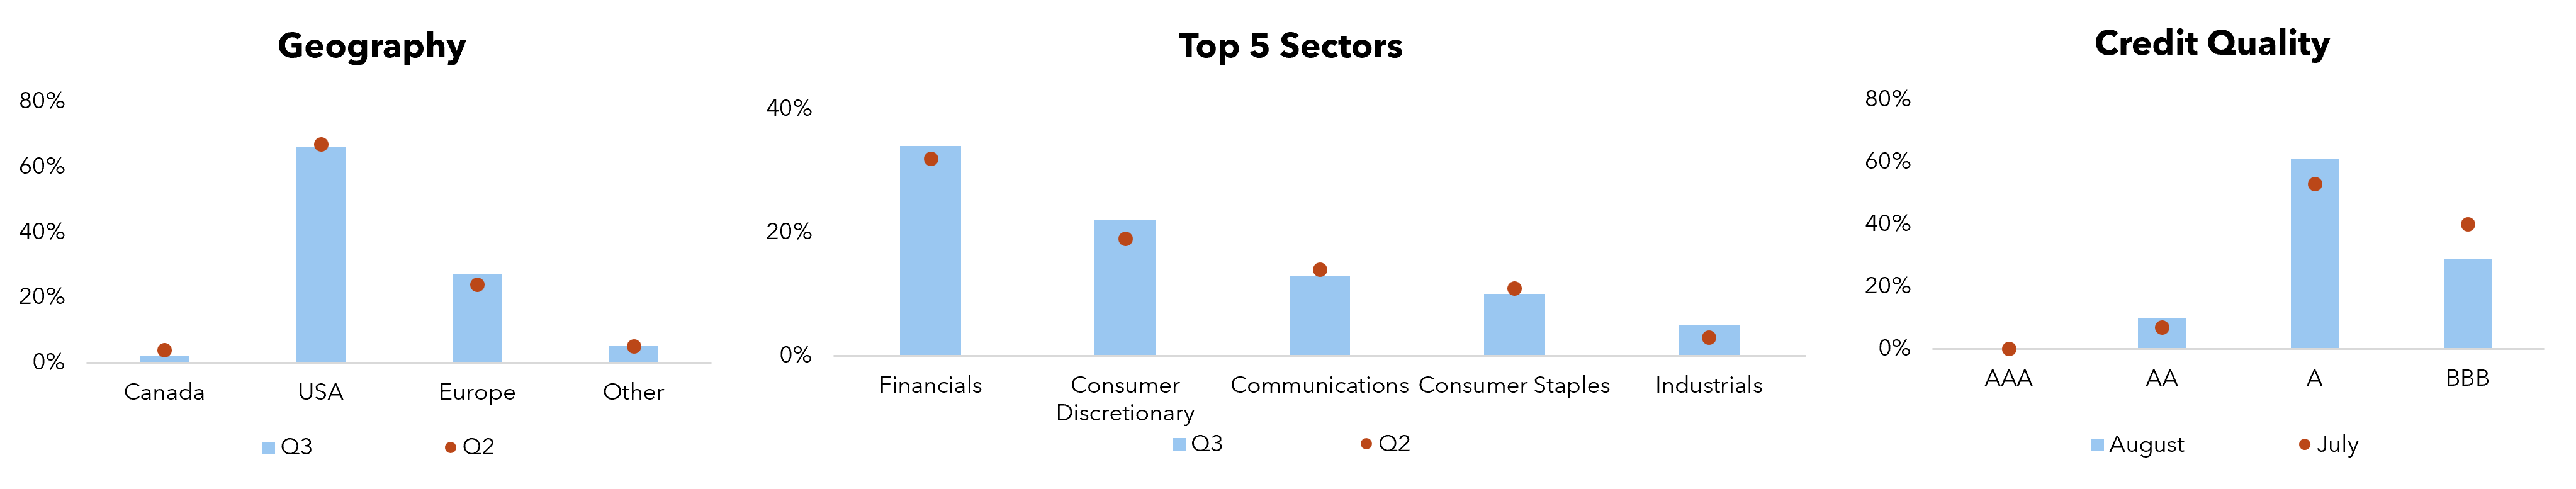
Source: RPIA. Data as of 9/30/2026.
RP Strategic Income Plus Fund
| 1 MON | 3 MON | 6 MON | YTD | 1 YR | 3 YR | 5 YR | 10 YR | Since Inception | |
|---|---|---|---|---|---|---|---|---|---|
| STIP Class F | -2.08% | -3.90% | -2.35% | -3.05% | -3.25% | 4.42% | 1.60% | 2.82% | 3.21% |
Source: RPIA. Data as of 9/30/2026. STIP Class F = RP Strategic Income Plus Fund Class F (RPD110). SI = 04/2016.
STIP returned -3.90% during the quarter as rising interest rates and widening credit spreads weighed on fixed income returns across markets.
Fixed income markets came under pressure in the third quarter as resilient economic data, persistent inflation concerns largely fueled by elevated energy prices, and a more hawkish policy outlook drove government bond yields materially higher. The selloff intensified in September, with government yield curves bear flattening as markets priced in a more aggressive tightening cycle. Credit spreads were comparatively resilient, supported by healthy corporate fundamentals and strong yield-based demand, but rising rate volatility increasingly weighed on conditions, and heavy issuance and concerns around AI-related financing created pockets of weakness. Overall, duration was the primary headwind across fixed income markets, while credit performance became more challenged toward quarter-end, particularly in lower-quality segments of the high yield market.
Rising risk-free rates were the main contributor to negative total returns, as STIP carried an interest rate duration of more than 6 years during the period. From a credit perspective, widening spreads were a net drag, though mark-to-market losses were partially offset by attractive carry from elevated all-in corporate yields.
The portfolio’s Canadian credit exposure contributed positively, led by energy utilities and consumer staples. Within utilities, spreads on long-held, high-conviction positions in power-generation issuers such as BPC Generation Infrastructure Trust and Maple bonds issued by Électricité de France performed well. Debt issued by domestic telecom companies, including Bell and Rogers, was among the top contributors within the portfolio’s TMT holdings as spreads rallied into quarter-end. Canadian REIT debt also contributed positively, including Choice Properties REIT, where spreads have rallied since the announcement of its planned acquisition of First Capital REIT.
US credit exposure was more challenged, specifically across technology and media, where heavy issuance created technical pressure. This was particularly evident among AI-related hyperscalers and media & entertainment issuers, where significant capital requirements to fund the next generation of digital infrastructure, alongside M&A-related financing, drove elevated supply. Select AI-related exposures nevertheless performed well. Sopaipilla, A-rated data center debt financing a BlackRock-led joint venture with Meta as the tenant, was the portfolio’s top credit contributor during the quarter. The portfolio participated at an attractive new issue spread and fully monetized the position following substantial spread compression.
| Top Contributors to Credit Return (Sector) |
|---|
Utilities |
| Energy |
| Consumer Staples |
Source: RPIA. Data as of 9/30/2026.
| Top Contributors to Credit Return (Issuer) |
|---|
| Sopaipilla Investor LLC |
| BPC Generation Infrastructure Trust |
| Électricité de France SA |
With interest rates comprising a significant portion of all-in corporate bond yields and index-level credit spreads remaining near historical tights, the portfolio maintains an above-average duration stance, reflecting our view that the more attractive risk/return opportunity currently lies in rates. Accordingly, rate duration remained relatively stable at approximately 6.3 years, while the credit risk of the portfolio remains lower than average. Moreover, the portfolio’s yield to maturity increased from 4.1% to 4.9% during the quarter, providing higher carry and margin of safety, and greatly improving the forward-looking return profile.
Credit exposure remained relatively measured, reflecting the team’s current preference to maintain higher-than-average outright duration exposure while remaining more selective on credit. The portfolio also maintains a pronounced up-in-quality bias, with approximately 97% of holdings rated investment grade.
Geographic positioning evolved more meaningfully during the quarter, with well-performing Canadian exposure reduced in favour of increased US and European exposure; the latter is concentrated in high-quality bank debt offering attractive relative value. Sector positioning remains diversified overall, with financials representing the portfolio’s largest exposure, complemented by meaningful allocations to energy utilities and TMT-related sectors. Within TMT and AI-related credit, the portfolio continues to differentiate across issuers and structures rather than maintain broad thematic exposure, reducing more generic risk while retaining positions where technical pressure or structural protections create compelling relative value. Overall, the portfolio remains focused on harvesting elevated all-in yields while preserving the capacity to add credit risk selectively as volatility creates more attractive entry points.
| Q3 2026 | Q2 2026 | |
|---|---|---|
| Yield to Maturity (CAD) | 4.9% | 4.1% |
| Yield to Maturity (Local) | 5.5% | 4.6% |
| Effective Duration (Years) | 6.3 | 6.3 |
| Credit Duration (Years) | 5.3 | 5.6 |
| % Rated Investment Grade | 97% | 98% |
Source: RPIA. Data as of 9/30/2026.
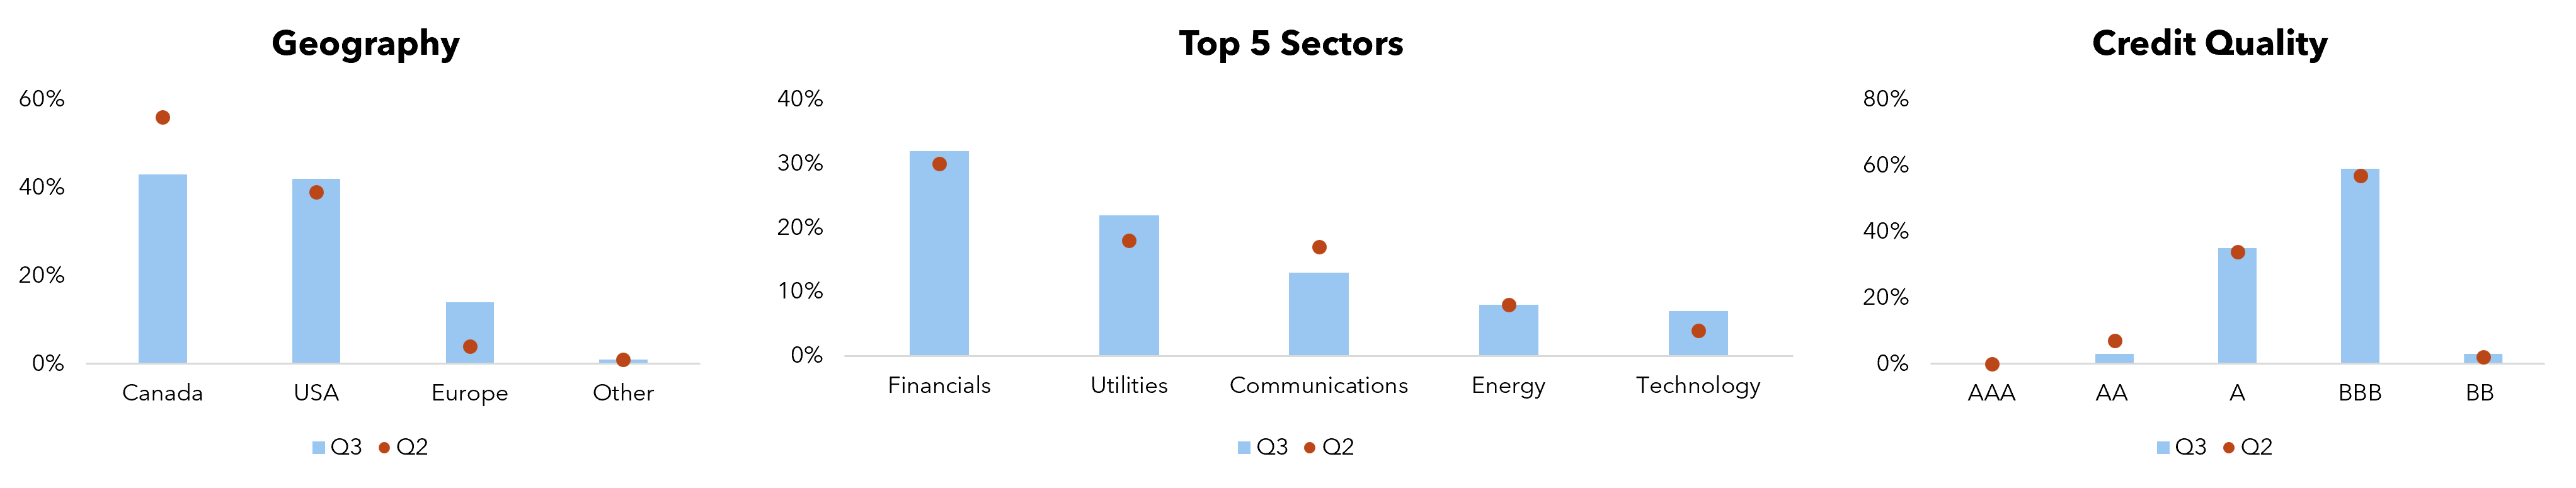
Source: RPIA. Data as of 9/30/2026.
RP Alternative Global Bond Fund
| 1 MON | 3 MON | 6 MON | YTD | 1 YR | 3 YR | 5 YR | Since Inception | |
|---|---|---|---|---|---|---|---|---|
| Class F | -3.20% | -4.04% | -1.95% | -3.19% | -3.14% | 5.82% | 4.09% | 5.27% |
Source: RPIA. Data as of 9/30/2026. AGB Class F = RP Alternative Global Bond Fund Class F (RPD210). SI = 07/2019.
AGB returned -4.04% during the quarter as rising interest rates and widening credit spreads weighed on fixed income returns across markets.
Fixed income markets came under pressure in the third quarter as resilient economic data, persistent inflation concerns largely fueled by elevated energy prices, and a more hawkish policy outlook drove government bond yields materially higher. The selloff intensified in September, with government yield curves bear flattening as markets priced in a more aggressive tightening cycle. Credit spreads were comparatively resilient, supported by healthy corporate fundamentals and strong yield-based demand, but rising rate volatility increasingly weighed on conditions, and heavy issuance and concerns around AI-related financing created pockets of weakness. Overall, duration was the primary headwind across fixed income markets, while credit performance became more challenged toward quarter-end, particularly in lower-quality segments of the high yield market.
AGB total returns were challenged mainly by rising rates, given the portfolio's concentration in front-end interest rate duration. From a credit perspective, AGB experienced mark-to-market losses from wider spreads, partially offset by positive returns from active trading and attractive carry from elevated all-in corporate yields.
Specific to credit returns, health care exposures were the largest contributors, led by new issues from financing vehicles associated with large industry participants, where attractive new issue valuations and subsequent spread performance supported returns. Industrial exposures also contributed positively, led by a newly issued Heathrow holding company (HoldCo) bond purchased at an attractive ~140 bps spread premium to comparable operating company (OpCo) debt, which subsequently outperformed as the differential compressed by ~40 bps.
Exposure to TMT-related debt resulted in bifurcated performance and was a net detractor overall, as heavy issuance created technical pressure across global credit markets. This was particularly evident across AI-related hyperscalers and media & entertainment issuers, where significant capital requirements to fund the next generation of digital infrastructure, alongside M&A-related financing, drove elevated supply.
Select AI-related debt exposures performed well during the period. In particular, Sopaipilla – A-rated data center debt for a BlackRock-led joint venture with Meta as the tenant – was the portfolio’s top credit contributor during the quarter. The portfolio capitalized on an attractive new issue spread and fully monetized the position following substantial spread compression. The portfolio’s diversified hedging overlay was a net detractor during the quarter, but provided meaningful downside protection as credit spreads widened more broadly toward quarter-end.
| Top Contributors to Credit Return (Sector) |
|---|
| Health Care |
| Industrials |
| Utilities |
Source: RPIA. Data as of 9/30/2026.
| Top Contributors to Credit Return (Issuer) |
|---|
| Sopaipilla Investor LLC |
| CDX.ITRX.SUBFIN S46 12/31 |
| JPMorgan Chase & Co. |
With interest rates comprising a significant portion of all-in corporate bond yields and index-level credit spreads remaining near historical tights, the portfolio maintains an above-average duration stance, reflecting our view that the more attractive risk/return opportunity currently lies in rates. The portfolio constantly adjusts its duration exposures across rate markets and tenors based on the opportunity set. At present, duration is almost exclusively focused on the 2-year segment of the Canadian yield curve and the 5-year segment of the US Treasury curve, where we believe attractive carry, real yields, and elevated terminal-rate expectations provide a compelling entry point.
On the credit side, overall exposure remained measured, with net credit leverage of approximately 0.9x and 94% of the portfolio rated investment grade. The portfolio continued to emphasize an up-in-quality bias alongside a diversified hedging overlay, preserving the ability to selectively add risk while providing protection against broader market weakness. This approach reflects the team's increasingly valuation-sensitive stance as higher rates and volatility began to challenge credit markets toward quarter-end.
Geographically, the US remained the portfolio's largest market for spread exposure, reflecting the depth of the opportunity set and greater dispersion created by heavy issuance. The portfolio remained selective across AI-related hyperscaler and data center credit, reducing more generic exposures while retaining positions where technical pressure created attractive relative value. Canadian exposure remained focused on high-quality opportunities, while European risk was managed selectively, though we note that heightened sovereign and macro uncertainty are beginning to create pockets of opportunity. Overall, the portfolio continues to prioritize relative value and idiosyncratic opportunities over adding broad credit beta.
| Q3 2026 | Q2 2026 | |
|---|---|---|
| Effective Duration (Years) | 5.0 | 3.1 |
| Credit Duration (Years) | 4.5 | 5.3 |
| Net Credit Leverage | 0.9x | 0.9x |
| % Rated Investment Grade | 81% | 94% |
| Diversified Hedging Overlay (% of NAV) | -9% | -66% |
Source: RPIA. Data as of 9/30/2026.
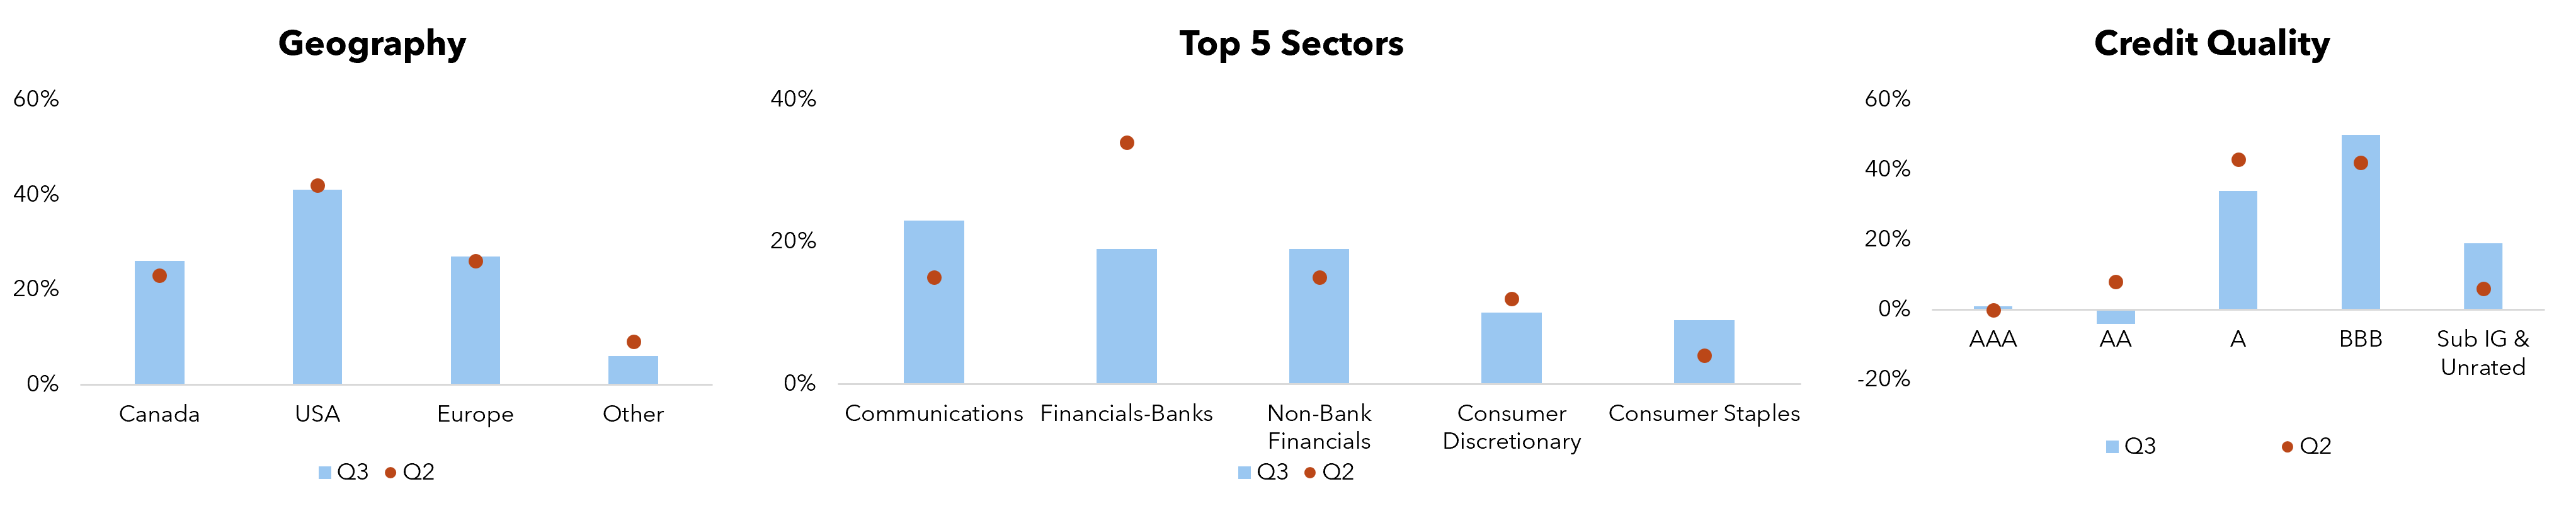
Source: RPIA. Data as of 9/30/2026.
RP Alternative Credit Opportunities Fund
Fixed income markets came under pressure in the third quarter as resilient economic data, persistent inflation concerns largely fueled by elevated energy prices, and a more hawkish policy outlook drove government bond yields materially higher. The selloff intensified in September, with government yield curves bear flattening as markets priced in a more aggressive tightening cycle. Credit spreads were comparatively resilient, supported by healthy corporate fundamentals and strong yield-based demand, but rising rate volatility increasingly weighed on conditions. Credit spreads began to weaken more noticeably toward quarter-end as tighter financial conditions took hold. The high yield market experienced greater dispersion, with lower-quality issuers coming under particular pressure as investors increasingly focused on leverage, refinancing risk, and balance sheet resilience, while higher-quality segments of the market remained comparatively well supported.
ACOF returns were challenged mainly in September as a sharp rise in risk-free yields drove increased volatility across high yield credit markets. Positive credit spread returns were driven by commercial finance and specialty financial services issuers. For example, Burford Capital, the world’s largest litigation finance firm and the portfolio’s top credit contributor during the period, issued a secured, investment grade rated 3-year bond in September with an 8% coupon. ACOF participated in the new issue given its attractive outright yield and relative valuation versus both Burford’s unsecured high yield debt and the comparable BB-rated high yield index yield of approximately 6.5%. Elsewhere in financials, attractively priced 5-year BDC debt continued to contribute positively, supported by improving redemption trends and slowing issuance, which reinforced our constructive view of select opportunities within the sector.
Credit returns outside of financials were mixed. Consumer staples and health care issuers were positive contributors, while consumer discretionary and airline-related credit detracted amid inflationary pressures and elevated oil prices. Positions in select European REIT issuers that performed well in previous quarters came under pressure in September as interest rate volatility spiked. However, select industrials contributed positively, including a newly issued Heathrow holding company (HoldCo) bond purchased at an attractive ~140 bps spread premium to comparable operating company (OpCo) debt, which subsequently outperformed as the differential compressed by ~40 bps.
Exposure to TMT-related debt was a net detractor overall, with AI-related hyperscalers and media & entertainment issuers particularly affected by heavy supply and broader technical pressure. Select AI-related exposures nevertheless performed well, led by Sopaipilla, A-rated data center debt financing a BlackRock-led joint venture with Meta as the tenant. The portfolio participated at an attractive new issue spread and fully monetized the position following substantial spread compression. The portfolio’s diversified hedging overlay was a net contributor during the quarter, providing downside protection as credit spreads widened more broadly toward quarter-end.
| Top Contributors to Credit Return (Sector) |
|---|
| Financials |
| Materials |
| Consumer Staples |
Source: RPIA. Data as of 9/30/2026.
| Top Contributors to Credit Return (Issuer) |
|---|
| Burford Capital Global Finance LLC |
| CDX.NA.HY.46 06/31 |
| Western Alliance Bank |
The Fund continues to source its modest interest rate exposure primarily from the front end of the US yield curve, reflecting our preference for the attractive all-in yields available in shorter-duration BBB- to B-rated credit. Spread exposure also remains focused on US credit with maturities of 10 years or less. This positioning allows the Fund to capture attractive carry and potential upside from front-end rates without materially extending its maturity profile.
The Fund selectively increased credit exposure during the quarter as greater market dispersion created more attractive entry points. Accordingly, high yield exposure increased modestly, but remains concentrated in BB- and B-rated issuers, with limited exposure to the lowest-quality segments of the market. This remains particularly important as higher rates and tighter financial conditions increasingly pressure more leveraged issuers and refinancing-sensitive credits. Importantly, nearly all of the portfolio’s “unrated” exposure consists of pre-deal SPAC investments backed by cash held in trust, which is typically invested in US government securities.
The portfolio continues to maintain a diversified hedging overlay, including single-name shorts and macro credit products, as broader credit valuations remain relatively tight. We believe this combination of higher-quality carry, idiosyncratic long positions, and meaningful downside protection leaves the Fund well positioned to capitalize on further market dislocations.
| Q3 2026 | Q2 2026 | |
|---|---|---|
| Effective Duration (Years) | 1.9 | 1.1 |
| Credit Duration (Years) | 3.2 | 3.1 |
| Average Term (Years) | 3.4 | 4.0 |
| Net Credit Leverage | 1.4x | 1.2x |
| % Rated Investment Grade | 24% | 30% |
| Diversified Hedging Overlay (% of NAV) | -35% | -43% |
Source: RPIA. Data as of 9/30/2026.
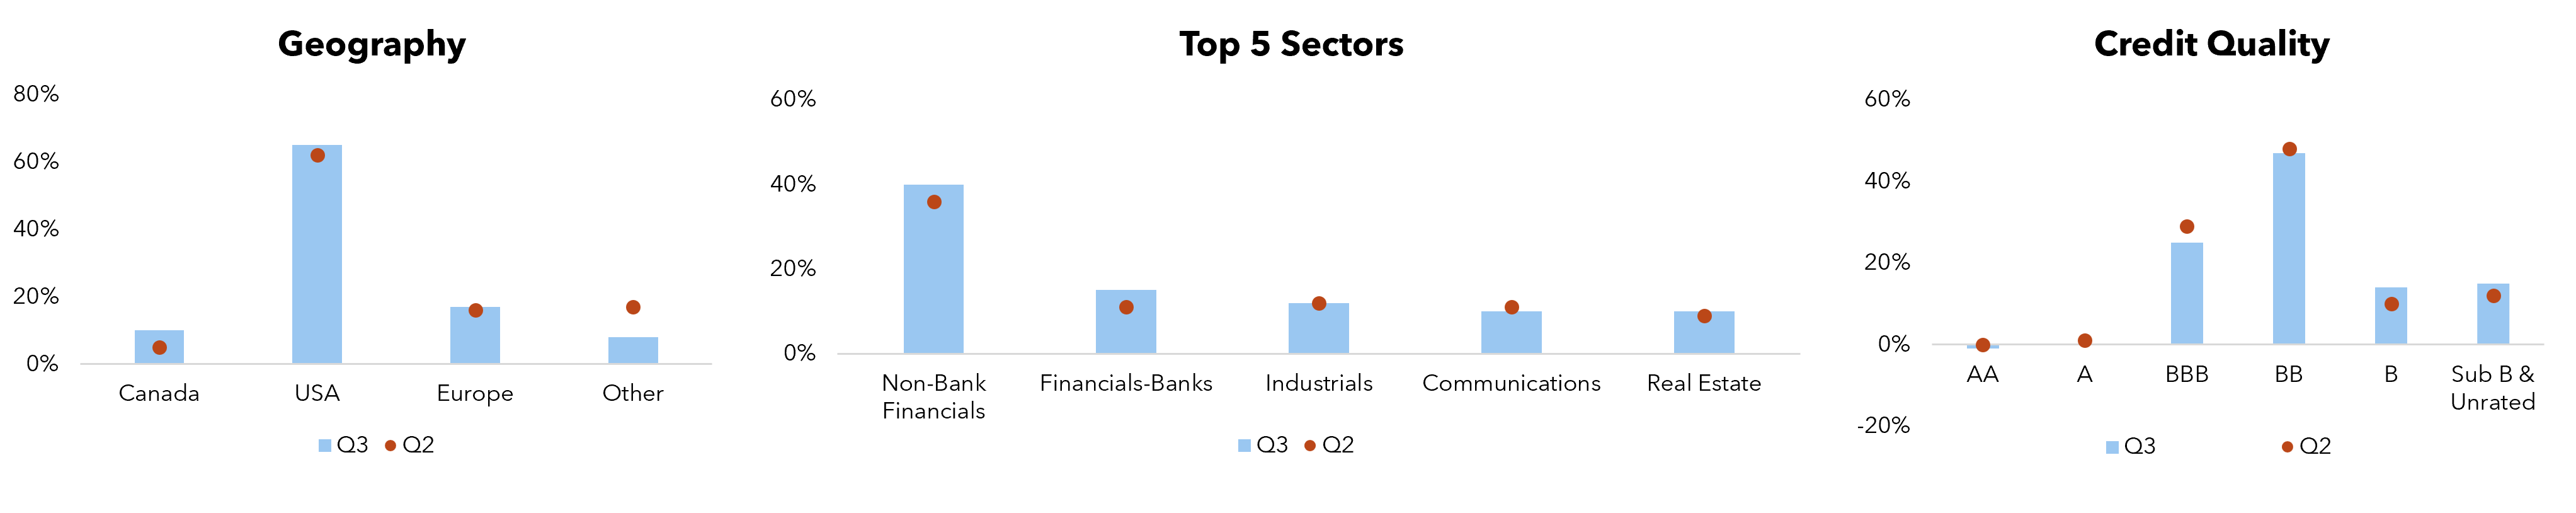
Source: RPIA. Data as of 9/30/2026.